Spray Foam Insulation and Mortgages: What Homeowners Need to Know
Updated:

If you’re trying to remortgage a home with spray foam insulation, you’ve probably discovered it can be more complicated than expected. While spray foam is effective for improving energy efficiency, it has become a major red flag for many UK lenders. Understanding why (and what you can do about it) is essential if you want to move forward with a successful spray foam insulation mortgage application.
Why Spray Foam Insulation Affects Mortgages
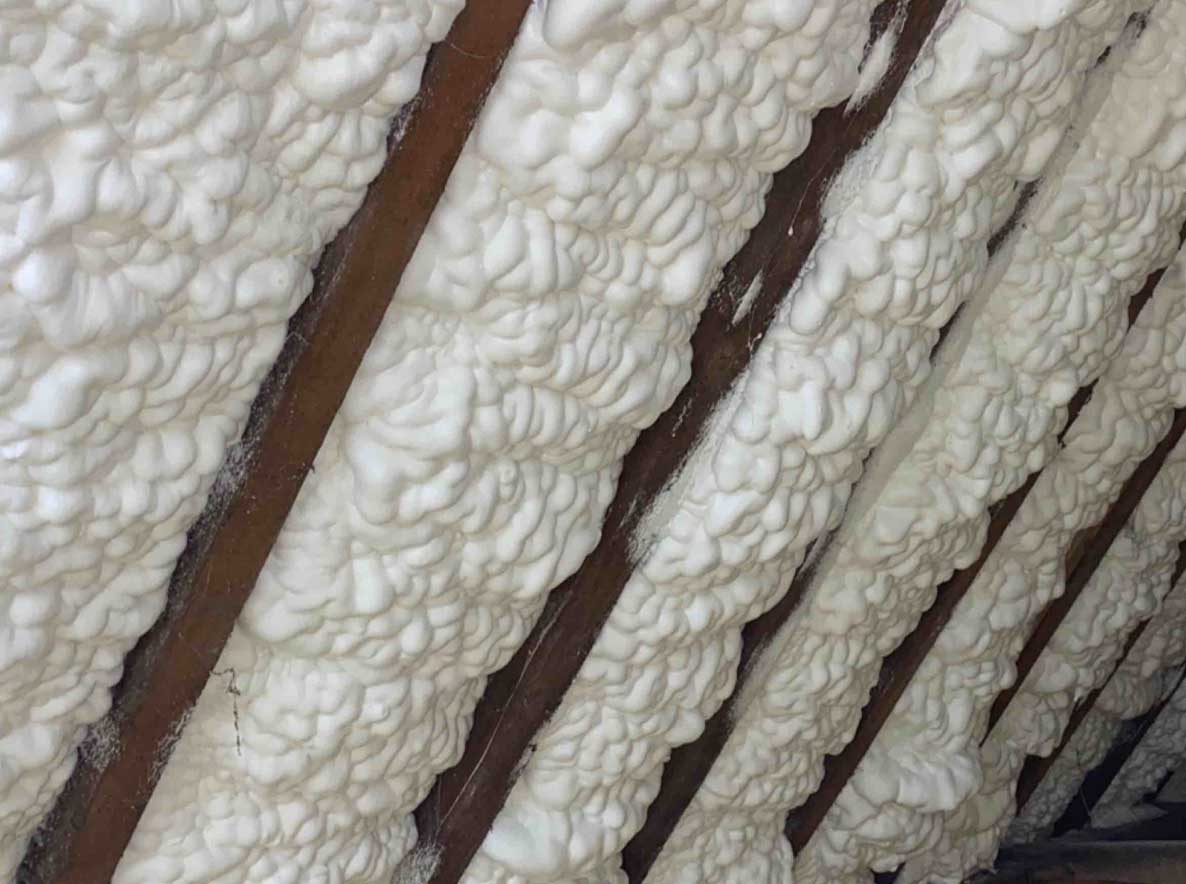
Mortgage lenders and surveyors are often cautious when it comes to spray foam. The main concern is that it can trap moisture and hide potential roof or timber damage, particularly when installed on the underside of a pitched roof. Because surveyors can’t inspect the rafters or check for damp, lenders may classify the property as high-risk.
In many cases, this means your remortgage or property sale could be delayed or declined until the insulation issue is resolved.
The Value of a Professional Spray Foam Assessment
Before applying for a new mortgage or remortgage, it’s wise to arrange a professional spray foam inspection. A qualified specialist can determine whether your insulation is causing structural or ventilation problems and produce a detailed report.
This report can:
- Help identify hidden damage early
- Give you clear options for removal or remediation
- Provide evidence to reassure lenders about the condition of your home
At Remove Spray Foam Ltd, our expert team carries out thorough inspections and provides honest, practical advice to help you move forward confidently.
What Are Your Options?
If you’re struggling to secure a spray foam insulation mortgage, you still have several routes to explore:
-
Remove the Spray Foam Insulation
The most reliable solution is full removal. Once the foam is professionally removed and the roof timbers are visible again, lenders are typically happy to proceed. Spray foam removal also restores your property’s marketability if you plan to sell your spray foam home in the future.
-
Use a Specialist Lender
Some mortgage providers are familiar with spray foam issues and may consider applications on a case-by-case basis. These lenders often require a professional report or proof of safe installation - something we can help you obtain.
-
Strengthen Your Property Documentation
Keep all relevant paperwork, including installation records, product details, and inspection reports. Clear documentation helps demonstrate that your property is safe and well maintained.
The Bottom Line
Having spray foam insulation doesn’t mean you can’t remortgage, but it does mean you’ll need to take extra steps. By arranging an expert inspection or removing the spray foam entirely, you can make your property mortgage-ready and avoid unnecessary delays.
If your spray foam insulation mortgage has been declined or delayed, contact Remove Spray Foam Ltd today. Our specialists can assess your situation, recommend the best course of action, and help you get back on track toward approval.